Market Signal Desk · Updated 2026-09-27
Weekend Signal Map: Chips, AI Drug Discovery, and Monday’s Setup
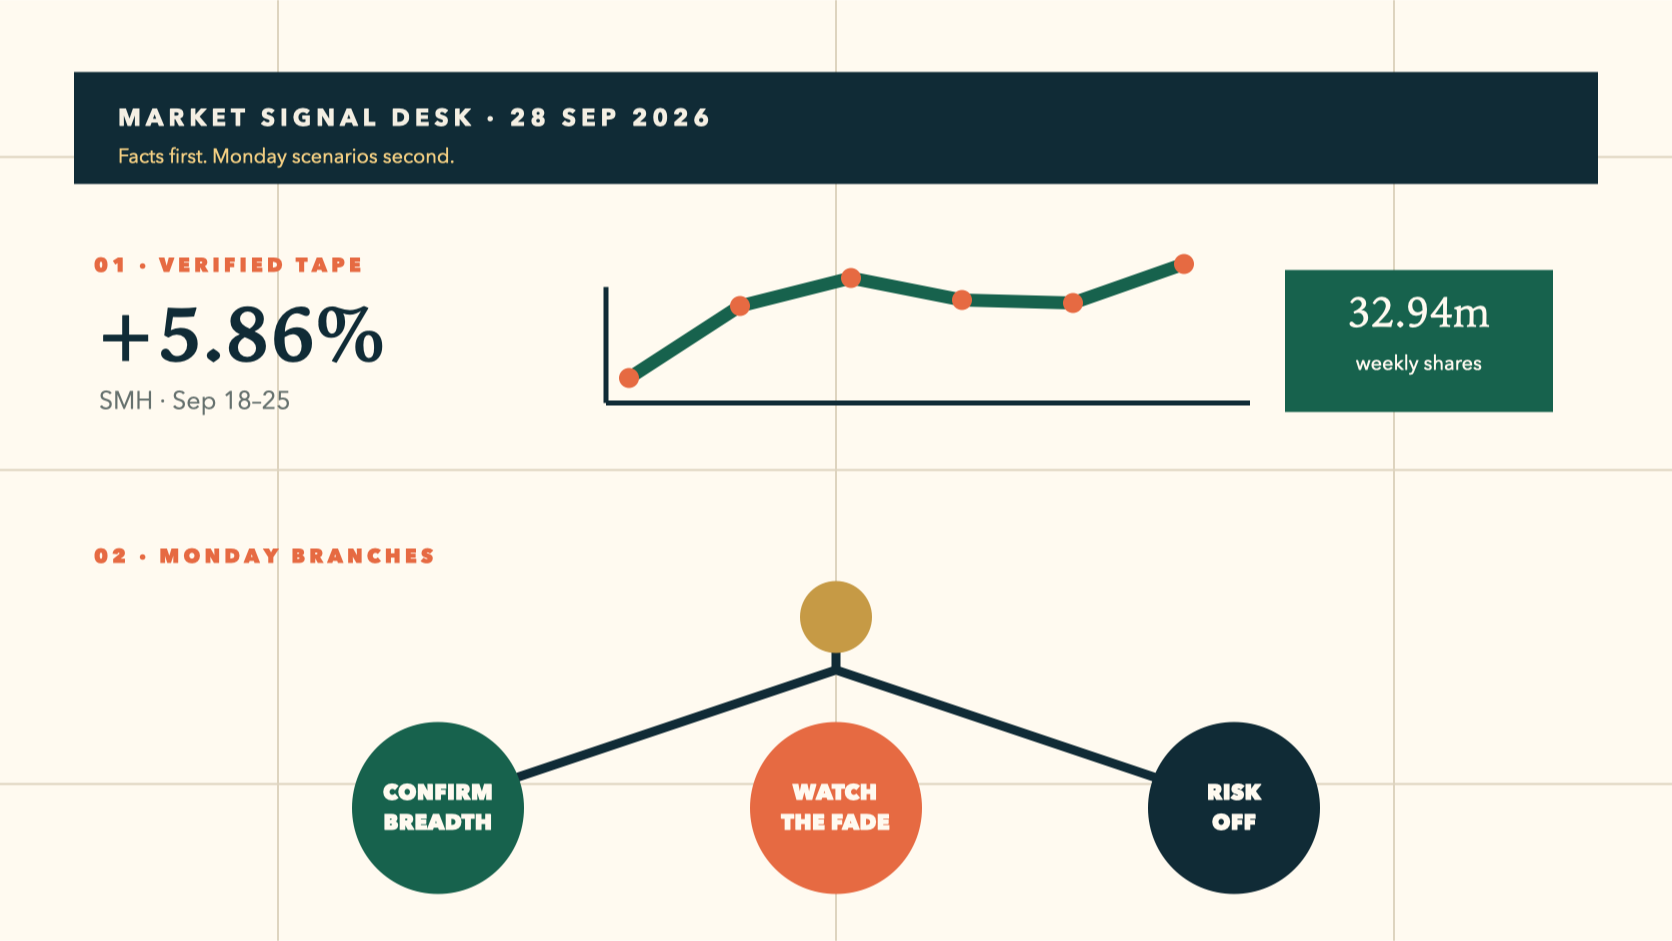
The tape confirms two active themes into Monday: U.S. semiconductors and China’s healthcare chain, especially medical services, biologics, and chemical pharmaceuticals. Weekend U.S.–China AI dialogue announcements support the technology narrative, but they did not cause the preceding rally. MLCC remains a watch item because its short listed history did not clear our 5% weekly confirmation threshold. The Monday view below is a scenario map—not a forecast presented as fact.
The evidence window and the filter
This brief separates the weekend information window from the market-performance window. Weekend facts are limited to Friday afternoon through Monday morning in Beijing. A sector is called a confirmed leader only when a broad, investable proxy or sector measure gained at least 5% over the latest comparable week and trading activity was substantial. Company anecdotes and social-media claims do not pass that filter on their own.
Fact: U.S. semiconductors cleared the price and activity screen
VanEck Semiconductor ETF closed at 606.56 on September 25, up 5.86% from 573.00 on September 18. About 32.94 million shares changed hands during September 21–25, or roughly 6.59 million per session. The combination of a greater-than-5% weekly rise and multi-million-share daily turnover clears this column’s price-and-activity screen.
Fact: China’s healthcare chain also cleared the screen
Through September 21, China’s medical-services sector rose 10.26% across five sessions, chemical pharmaceuticals gained 5.55%, and biologics advanced 8.10%. Reported daily turnover was about RMB 40.22 billion, RMB 50.24 billion, and RMB 20.82 billion respectively. The same session produced more than RMB 2 trillion in total A-share turnover, while policy coverage linked the pharmaceutical plan to AI, supercomputing, and computational medicine in drug research.
Fact: the weekend added an AI-policy bridge, not a retroactive cause
China’s foreign ministry said the two sides agreed to establish an AI dialogue, discuss benefits and risks, hold the next dialogue in November, and create an AI-incident communication channel. This is relevant to the technology narrative, but the semiconductor rally occurred before the weekend announcement. The careful interpretation is continuation support and lower communication friction—not proof that the announcement caused the prior price move.
Monday base case: leadership holds only if breadth confirms
The base case is continued attention in semiconductors and AI-enabled drug discovery, with higher opening volatility after strong weekly gains. Confirmation would require the leaders to hold relative strength beyond the opening burst, participation to extend beyond a few large names, and turnover to remain healthy. If price rises while breadth narrows, the move is less reliable and chasing risk increases.
China setup: healthcare can stay active, but a pullback is normal
For A-shares, the constructive case is that medical services, biologics, and chemical pharmaceuticals retain above-market turnover and a wide advancer base after the September 28 reopen. The invalidation signal is an early surge that loses volume support or concentrates in only a few names. Because parts of the chain already gained 5%–10% in five sessions, a pullback would not by itself disprove the theme; collapsing breadth would matter more.
MLCC stays on the watchlist, not the leader board
A historical close series for the newly launched Global X MLCC and Electronic Components ETF shows a move from 50.56 on September 18 to 51.38 on September 25, a 1.62% gain. That does not clear the 5% screen, and the fund’s short history makes broad conclusions especially fragile. A-share component names also showed mixed price action, so the theme needs fresh breadth, expanding turnover, and a primary company or industry announcement before promotion. Unverified claims of 30%–80% price increases are excluded.
Risk-off branch: yields, oil, or weak liquidity can reverse the setup
The risk-off branch activates if Treasury yields or oil prices rise sharply, if broad market liquidity contracts, or if technology opens strong and quickly loses participation. OPEC’s next meeting is scheduled for October 4, so energy expectations may become more important as the week progresses. Monday’s job is to test the scenario against live evidence, not defend a fixed prediction.
Common questions
No. This is a market-structure and news-evidence brief. It does not account for an individual reader’s objectives, risk tolerance, holdings, or time horizon.
The verifiable close series gained 1.62% over the comparison window, below the stated 5% threshold, while individual A-share components showed mixed action. The evidence supports monitoring, not upgrading it to a confirmed theme.
A sharp change in rates or oil, weak opening breadth, shrinking turnover, or rapid loss of relative strength would weaken the constructive case. Broad participation and sustained liquidity would strengthen it.